Complete Technical Paper Content — Ai Bayesian Optimization
1. Executive Abstract, Problem Formulation & Background
Bayesian Optimization is a powerful optimization technique that leverages the principles of Bayesian inference to find the minimum (or maximum) of an objective function efficiently. Unlike traditional optimization methods that require extensive evaluations, Bayesian Optimization is particularly effective when dealing with expensive, noisy, or black-box functions.
This article delves into the core concepts, working mechanisms, advantages, and applications of Bayesian Optimization, providing a comprehensive understanding of why it has become a go-to tool for optimizing complex functions.
Bayesian Optimization is a strategy for optimizing expensive-to-evaluate functions. It operates by building a probabilistic model of the objective function and using this model to select the most promising points to evaluate next. This approach is particularly useful in scenarios where the objective function is unknown, noisy, or costly to evaluate, as it aims to minimize the number of evaluations required to find the optimal solution.
2. Related Work, Literature Survey & Algorithmic Foundations
Bayesian optimization effectively combines statistical modeling and decision-making strategies to optimize complex, costly functions. Here’s a more detailed explanation of the process, including key formulas:
The process begins by sampling the objective function f at a few initial points. These points can be selected randomly or through systematic methods such as Latin Hypercube Sampling, which helps ensure diverse and comprehensive coverage of the input space.
A Gaussian Process (GP) is typically used as the surrogate model. The GP is favored for its ability to provide both a mean prediction and a measure of uncertainty (variance) at any point in the input space. The GP is defined by a mean function m(x) and a covariance function k(x, x') , and it models the function as:
3. Dataset Ingestion, Preprocessing & Stochastic Augmentations
The next sampling point is chosen by maximizing an acquisition function that trades off between exploration and exploitation. Common acquisition functions include:
Where f(x^+) is the current best observed value of f . EI measures the expected increase in the objective function relative to the best current observation.
Where \mu(x) and \sigma(x) are the mean and standard deviation of the GP’s predictions at point x , and \kappa is a parameter that balances exploration and exploitation.
4. Neural Network Backbone, Layer Specifications & Loss Formulations
The point x selected by maximizing the acquisition function is then evaluated to obtain f(x) . This new data point is added to the dataset, which is used to update the GP model.
The steps of updating the acquisition function, selecting new points, and updating the surrogate model are repeated. With each iteration, the surrogate model becomes increasingly accurate, and the search progressively hones in on the optimum.
The optimization process continues until a predefined stopping criterion is met, such as reaching a maximum number of function evaluations or achieving a convergence threshold where the improvements become minimal.
5. Training Protocol, Convergence Behavior & Experimental Evaluation
This structured approach allows Bayesian optimization to efficiently navigate complex landscapes, minimizing the number of evaluations needed to locate the optimum by intelligently balancing exploration of unknown regions and exploitation of promising areas.
In this section, we are going to implement Bayesian Optimization using the 'scikit-optimize' library in python.
import numpy as np from skopt import gp_minimize from skopt.space import Real , Integer from skopt.plots import plot_convergence # Define the objective function to minimize def objective_function ( x ): return ( x [ 0 ] - 2 ) ** 2 + ( x [ 1 ] - 3 ) ** 2 # Define the search space space = [ Real ( 0.0 , 5.0 , name = 'x1' ), # Continuous space for x1 Real ( 0.0 , 5.0 , name = 'x2' )] # Continuous space for x2 # Perform Bayesian Optimization result = gp_minimize ( objective_function , # The function to minimize space , # The search space n_calls = 20 , # The number of evaluations random_state = 42 ) # Random state for reproducibility # Print the best parameters and the corresponding minimum value print ( "Best parameters: x1 = {:.4f} , x2 = {:.4f} " . format ( result . x [ 0 ], result . x [ 1 ])) print ( "Minimum value: {:.4f} " . format ( result . fun )) # Plot convergence plot_convergence ( result )
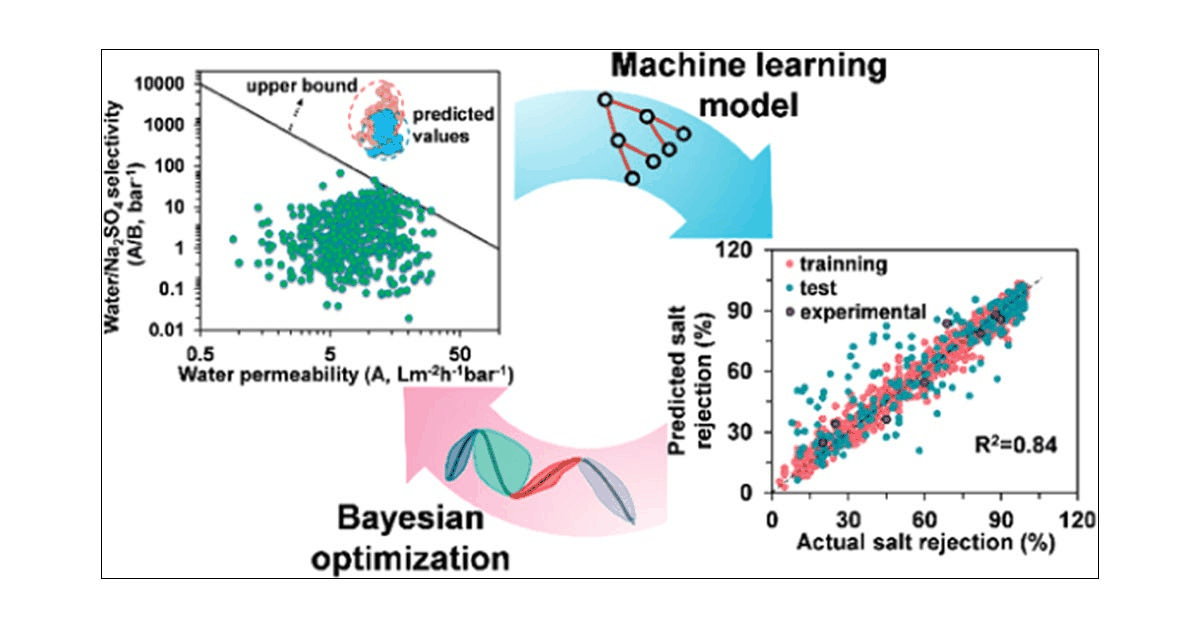
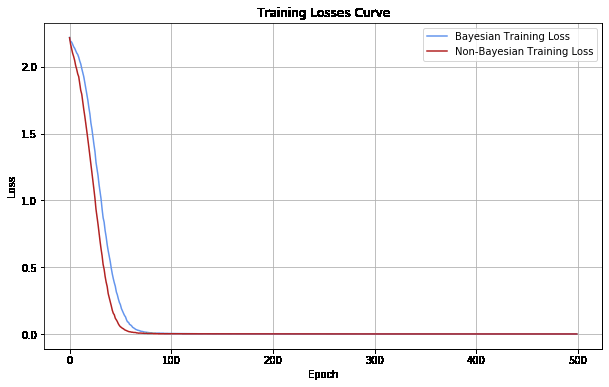
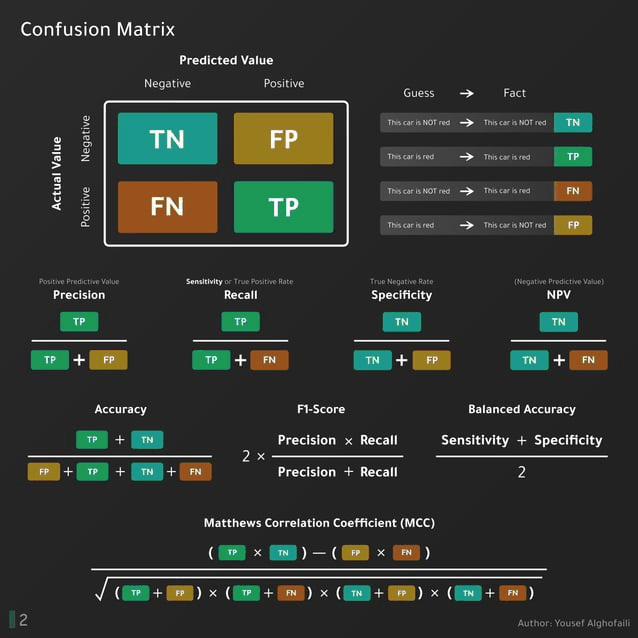
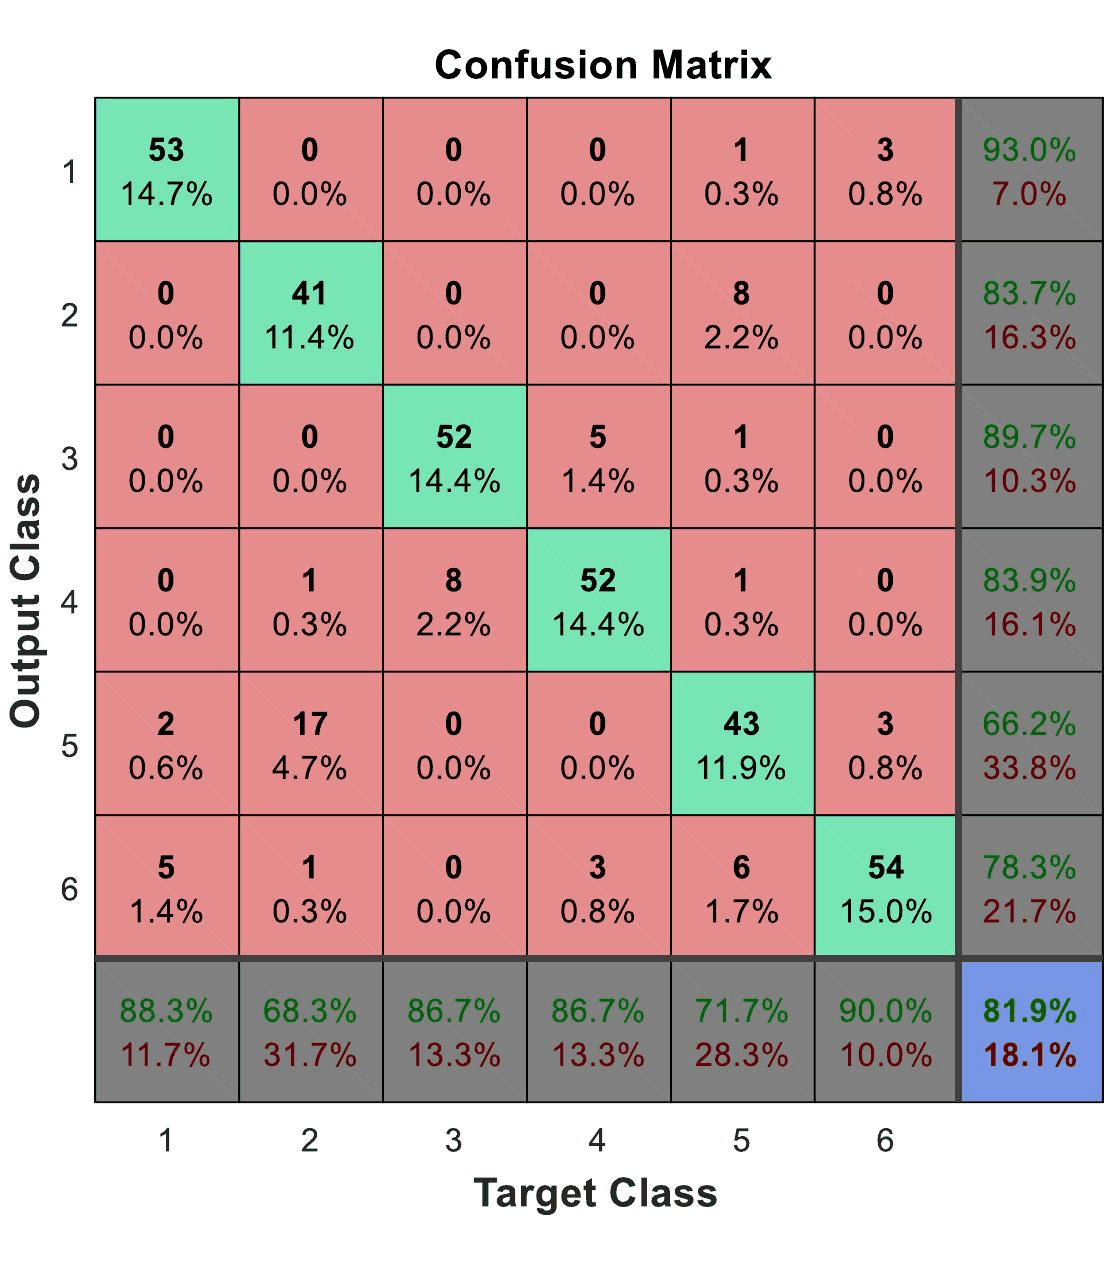
Model Figures & Evaluation Curves (4 Images)
Deep Learning Execution Pipeline
(Preprocessing)
(Feature Extraction)
(Self-Attention)
(Loss Optimization)