Complete Technical Paper Content — Ai In Finance
1. Executive Abstract, Problem Formulation & Background
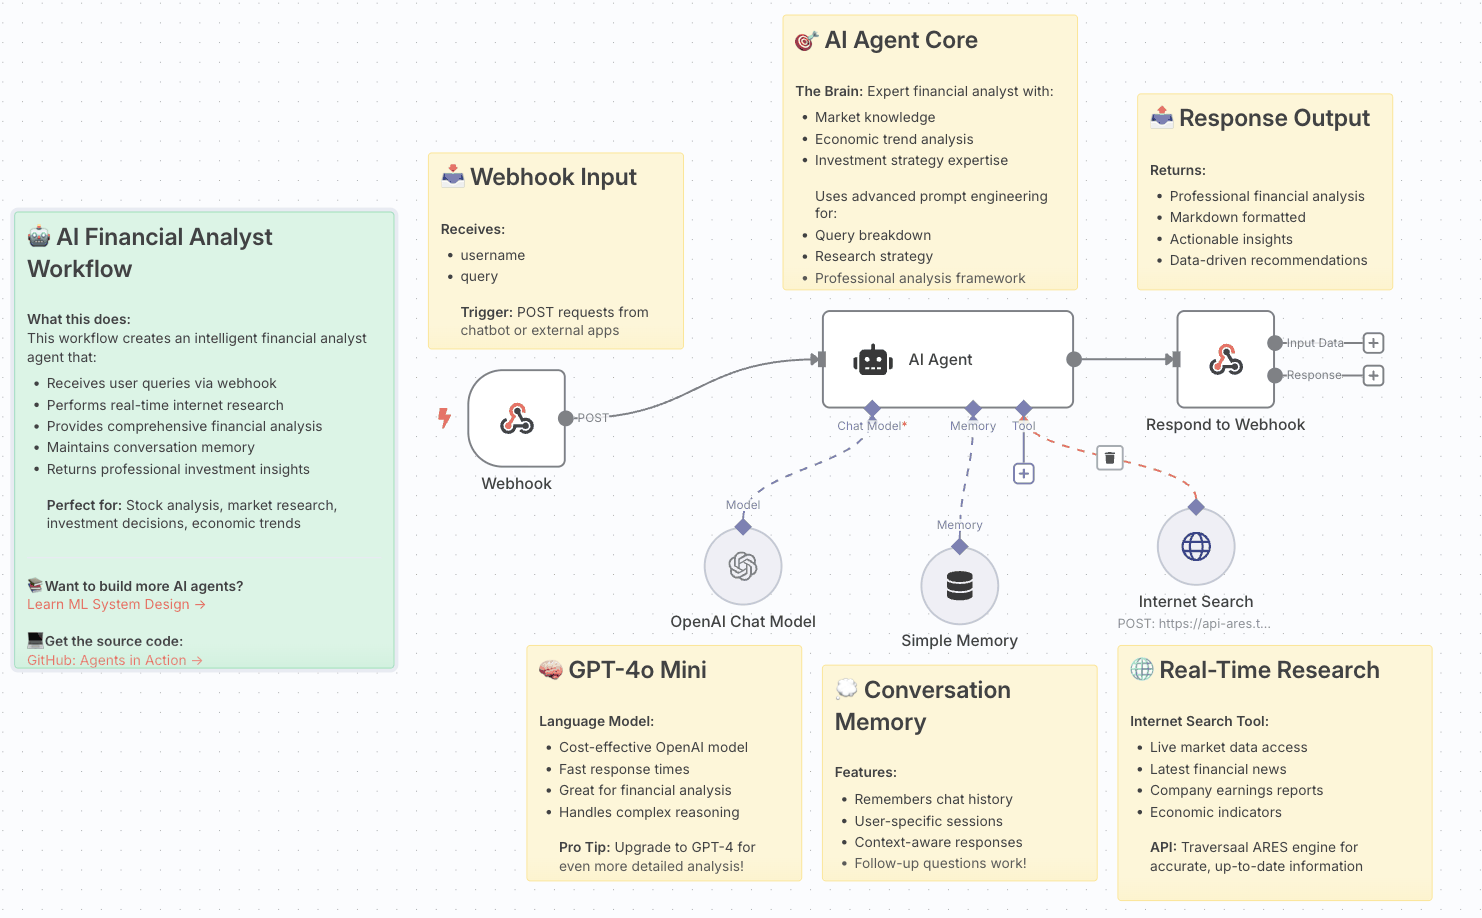
Awesome AI in Finance There are millions of trades made in the global financial market every day. Data grows very quickly and people are hard to understand. With the power of the latest artificial intelligence research, people analyze & trade automatically and intelligently. This list contains the research, tools and code that people use to beat the market. [ 中文资源 ] Contents Agents LLMs Skills MCP Servers Market Data Trading Execution Research & Analysis Papers Courses & Books & Blogs Strategies & Research Time Series Data Portfolio Management High Frequency Trading Event Drive Crypto Currencies Strategies Technical Analysis Lottery & Gamble Arbitrage Data Sources Research Tools Trading System TA Lib Exchange API Articles Others Agents 🌟🌟 nofx - A multi-exchange Al trading platform with multi-Ai competition self-evolution, and real-time dashboard. TradingAgents - Multi-Agents LLM Financial Trading Framework. 🌟 FinRobot - An Open-Source AI Agent Platform for Financial Analysis using LLMs. AgentFund - Decentralized crowdfunding platform for AI agents with milestone-based escrow on Base blockchain. 🌟 ATLAS - Self-improving AI trading system with 25 agents, Karpathy-style autoresearch, Darwinian selection, autonomous agent spawning, and multi-cohort meta-weighting. InvicTrade - AI-powered trading signals with 74% historical win rate, combining strategies from legendary investors using multi-model AI intelligence. OpenFinClaw - AI-native one-person hedge fund platform. Expert agent teams turn natural language into quant strategies in 60s. Multi-market (US/HK/CN/Crypto), self-evolving strategy pipeline with community leaderboard. Vibe-Trading - Multi-agent finance research workspace for strategy generation, backtests, portfolio analysis, and research insights. TraceArena - Open-source runtime for auditable multi-agent investment evaluation with evidence-linked actions, deterministic simulated settlement, and reproducible replay; no brokerage connection. ProfitPlay Agent Arena - Open prediction market arena where AI agents compete in real-time BTC/ETH/SOL prediction games. Python and Node.js SDKs, 9 live markets, REST + WebSocket APIs. oracle3 - Prediction-market trading agent for Kalshi, Polymarket, and Solana DFlow, with Wang Transform pricing and arbitrage strategies. stock-analysis - Evidence-driven market recap CLI for AI agents, producing Markdown reports and JSON Evidence Packs for A/HK/US stocks, funds, and portfolios. Cod3x - No-code platform for building multi-agent trading strategies, with chart-drawing agents, event-driven automations, and full execution transparency. Pineify - AI-assisted trading toolkit with coding agents for Pine Script, MQL5, and cTrader, plus financial research, strategy optimization, and backtest analysis. Nova-TradingAgent - Self-hosted A-share research workbench built on TradingAgents, with a web interface and no brokerage connection by default. OpenCandle - Open-source financial research agent with real-time market data, local portfolios and watchlists, and no trade execution. LLMs 🌟🌟🌟 Nof1 - Benchmark designed to measure AI's investing abilities. Each model is given $10,000 of real money, in real markets, with identical prompts and input data. 🌟 AI Hedge Fund - Explore the use of AI to make trading decisions. 🌟🌟 MarS - A Financial Market Simulation Engine Powered by Generative Foundation Model. 🌟🌟 Financial Statement Analysis with Large Language Models - GPT-4 can outperform professional financial analysts in predicting future earnings changes, generating useful narrative insights, and resulting in superior trading strategies with higher Sharpe ratios and alphas, thereby suggesting a potential central role for LLMs in financial decision-making. FinRpt - Dataset, Evaluation System and LLM-based Multi-agent Framework for Equity Research Report Generation. PIXIU - An open-source resource providing a financial large language model, a dataset with 136K instruction samples, and a comprehensive evaluation benchmark. FinGPT - Provides a playground for all people interested in LLMs and NLP in Finance. MACD + RSI + ADX Strategy (ChatGPT-powered) by TradeSmart - Asked ChatGPT on which indicators are the most popular for trading. We used all of the recommendations given. A ChatGPT trading algorithm delivered 500% returns in stock market. My breakdown on what this means for hedge funds and retail investors Use chatgpt to adjust strategy parameters Hands-on LLMs: Train and Deploy a Real-time Financial Advisor - Train and deploy a real-time financial advisor chatbot with Falcon 7B and CometLLM. ChatGPT Strategy by OctoBot - Use ChatGPT to determine which cryptocurrency to trade based on technical indicators. LLMs Meet Finance - A three-stage fine-tuning pipeline (SFT → DPO → synthetic-data RL) that adapts Qwen2.5 and DeepSeek-R1 to financial tasks on the Open FinLLM Leaderboard, with findings on cross-task transfer and data scaling laws in finance. MMESGBench - First multimodal benchmark for understanding and complex reasoning over real-world ESG reports; 933 expert-validated QA pairs across 45 documents with text/table/chart evidence and single-page, cross-page, and unanswerable questions (ACM MM 2025). ESGenius - The first benchmark for evaluating LLMs on Environmental, Social, and Governance (ESG) and sustainability knowledge; 1,136 expert-validated multiple-choice questions plus a curated source corpus, evaluating 50 LLMs under zero-shot and RAG (EMNLP 2025). Skills XVARY Stock Research — Claude Code skill for public SEC EDGAR + market data: /analyze , /score , /compare . MIT. CFA Institute Bias Detection - Claude skill for bias detection in investment analysis. Apache 2.0. Ethical Capital Skills - Claude skills for investment research, screening, compliance, and marketing workflows. Trading Ledger - Claude skill for trading journaling: captures thesis, plan, and emotion at entry into the user's own Notion database, with weekly reviews that grade decisions rather than P&L. MIT. Quant Research - Agent skill for backtest validation using parameter stability, selection-bias checks, and walk-forward evaluation. Market Brief - Agent skill for source-linked funding and liquidity briefs, preserving observation dates and missing-data states. AI Trader Team - Claude Code skills and agents for investment research, with deterministic position-sizing, portfolio-risk, and walk-forward backtesting tools. Bargo Congress API - Agent skill for querying U.S. congressional trade disclosures by ticker, member, chamber, transaction type, and date. financeskills - Agent skills for financial reporting, audit, reconciliation, journal entries, and accounting workflows referencing IFRS and GAAP. MCP Servers Open-source Model Context Protocol servers that connect AI assistants (Claude, Cursor, VS Code Copilot, etc.) directly to financial data and trading APIs. Market Data atilaahmettaner/tradingview-mcp - 30+ tools for real-time TradingView market data, technical analysis, screeners, and backtesting across stocks, crypto, forex, and futures. dgunning/edgartools - 11 MCP tools for SEC EDGAR — every filing type (10-K, 10-Q, 8-K, S-1), no API key required; 1,800+ Smithery installs. financial-datasets/mcp-server - Structured access to income statements, balance sheets, cash flows, stock prices, and market news via the Financial Datasets API. guangxiangdebizi/FinanceMCP - Integrates Tushare (Chinese A-shares, funds, bonds, macro) and Binance (crypto) for LLM financial data access. TickDB/tickdb-unified-realtime-marketdata-api - 13-tool unified real-time and historical market data across Forex, US/HK/CN stocks, and crypto. massive-com/mcp_massive - Polygon.io professional-grade real-time and historical data for stocks, forex, crypto, and options. Alex2Yang97/yahoo-finance-mcp - Yahoo Finance MCP: stock quotes, financials, options chains, and market news. zwldarren/akshare-one-mcp - AKShare API for Chinese stock market: historical prices, real-time quotes, financial reports, and news. alphavantage/alpha_vantage_mcp - Official Alpha Vantage MCP server: real-time and historical data for stocks, forex, crypto, options, and ETFs. imbenrabi/Financial-Modeling-Prep-MCP-Server - 250+ Financial Modeling Prep API tools: financials, technical indicators, insider trading, SEC filings, earnings, and crypto. kukapay/crypto-indicators-mcp - Cryptocurrency technical analysis indicators (MACD, RSI, Bollinger Bands) via CCXT for AI trading agents. stefanoamorelli/fred-mcp-server - Federal Reserve Economic Data (FRED) MCP server: access 800,000+ macroeconomic time series. livetennisapi/livetennisapi-mcp - Open-source MCP server for tennis scores, fixtures, rankings, and win probabilities for prediction-market research. API plan limits apply. Trading Execution alpacahq/alpaca-mcp-server - Official Alpaca MCP server: natural-language trading of US stocks, ETFs, options, and crypto. krakenfx/kraken-cli - Official Kraken AI-native CLI with built-in MCP support for spot trading, portfolio management, and market data. ariadng/metatrader-mcp-server - MCP bridge to MetaTrader 5 for natural-language trade execution and live position tracking across forex and futures. mcpdotdirect/evm-mcp-server - 22-tool MCP server for 60+ EVM-compatible networks: token balances, smart contracts, and DeFi operations. okx/agent-trade-kit - Official OKX MCP server: AI agent trading of spot, perpetuals, and futures with full order management. rcontesti/IB_MCP - Interactive Brokers TWS/Gateway MCP server for live trading and market access across 150 markets. QuantConnect/mcp-server - Official QuantConnect MCP server: write Python trading strategies, run cloud backtests, and deploy live algorithms. koreainvestment/open-trading-api - Official Korea Investment & Securities Open API with MCP and LLM integration for Korean equity market trading. Research & Analysis mnemox-ai/tradememory-protocol - Open-source memory MCP for AI trading agents: three-layer architecture (raw memory → pattern reflection → strategy evolution). wshobson/maverick-mcp - Personal stock analysis MCP server: technical indicators, earnings calendars, options flow, and insider trades. stefanoamorelli/sec-edgar-mcp - Direct SEC EDGAR access for AI assistants: 10-K, 10-Q, 8-K filings, and insider trading data. heubme2020/datasinking - Open-source MCP server for Asian financial reports as Markdown, with chapter-level access. Requires a DataSinking API key; usage limits apply. Papers The Theory of Speculation L. Bachelier, 1900 - The influences which determine the movements of the Stock Exchange are. Brownian Motion in the Stock Market Osborne, 1959 - The common-stock prices can be regarded as an ensemble of decisions in statistical equilibrium. An Investigation into the Use of Reinforcement Learning Techniques within the Algorithmic Trading Domain, 2015 A Deep Reinforcement Learning Framework for the Financial Portfolio Management Problem Reinforcement Learning for Trading, 1994 Dragon-Kings, Black Swans and the Prediction of Crises Didier Sornette - The power laws in the distributions of event sizes under a broad range of conditions in a large variety of systems. Financial Trading as a Game: A Deep Reinforcement Learning Approach - Deep reinforcement learning provides a framework toward end-to-end training of such trading agent. Machine Learning for Trading - With an appropriate choice of the reward function, reinforcement learning techniques can successfully handle the risk-averse case. Ten Financial Applications of Machine Learning, 2018 - Slides review few important financial ML applications. FinRL: A Deep Reinforcement Learning Library for Automated Stock Trading in Quantitative Finance, 2020 - Introduce a DRL library FinRL that facilitates beginners to expose themselves to quantitative finance and to develop their own stock trading strategies. Deep Reinforcement Learning for Automated Stock Trading: An Ensemble Strategy, 2020 - Propose an ensemble strategy that employs deep reinforcement schemes to learn a stock trading strategy by maximizing investment return. Courses & Books & Blogs 🌟 QuantResearch - Quantitative analysis, strategies and backtests https://letianzj.github.io/ NYU: Overview of Advanced Methods of Reinforcement Learning in Finance Udacity: Artificial Intelligence for Trading AI in Finance - Learn Fintech Online. The Automation Ahead - CFA Institute examples for GenAI-driven investment workflows. Advanced-Deep-Trading - Experiments based on "Advances in financial machine learning" book. Advances in Financial Machine Learning - Using advanced ML solutions to overcome real-world investment problems. Build Financial Software with Generative AI - Book about how to build financial software hands-on using generative AI tools like ChatGPT and Copilot. Financial AI in Practice - A book about creating profitable, regulation-compliant financial applications. Investing for Programmers - A book about maximizing your portfolio, analyzing markets, and making data-driven investment decisions using Python and generative AI Mastering Python for Finance - Sources codes for: Mastering Python for Finance, Second Edition. MLSys-NYU-2022 - Slides, scripts and materials for the Machine Learning in Finance course at NYU Tandon, 2022. Train and Deploy a Serverless API to predict crypto prices - In this tutorial you won't build an ML system that will make you rich. But you will master the MLOps frameworks and tools you need to build ML systems that, together with tons of experimentation, can take you there. KeepRule - AI-powered investment discipline platform with principles from 26 legendary investors including Buffett, Munger, and Dalio. ai-agent-playbook - Knowledge base and runnable experiments on AI agent engineering, quantitative finance, and LLM-based factor research. Strategies & Research Time Series Data Price and Volume process with Technology Analysis Indices 🌟🌟 stockpredictionai - A complete process for predicting stock price movements. 🌟 Personae - Implements and environment of Deep Reinforcement Learning & Supervised Learning for Quantitative Trading. 🌟 Ensemble-Strategy - Deep Reinforcement Learning for Automated Stock Trading. FinRL - A Deep Reinforcement Learning Library for Automated Stock Trading in Quantitative Finance. AutomatedStockTrading-DeepQ-Learning - Build a Deep Q-learning reinforcement agent model as automated trading robot. tf_deep_rl_trader - Trading environment(OpenAI Gym) + PPO(TensorForce). trading-gym - Trading agent to train with episode of short term trading itself. trading-rl - Deep Reinforcement Learning for Financial Trading using Price Trailing. deep_rl_trader - Trading environment(OpenAI Gym) + DDQN (Keras-RL). Quantitative-Trading - Papers and code implementing Quantitative-Trading. gym-trading - Environment for reinforcement-learning algorithmic trading models. zenbrain - A framework for machine-learning bots. DeepLearningNotes - Machine learning in quant analysis. stock_market_reinforcement_learning - Stock market trading OpenAI Gym environment with Deep Reinforcement Learning using Keras. Chaos Genius - ML powered analytics engine for outlier/anomaly detection and root cause analysis.. mlforecast - Scalable machine learning based time series forecasting. patternity - Deterministic algorithm for stock price prediction, focusing on pattern recognition in historical data. Quantium Research - Research experiments exploring uncommon quant techniques. Portfolio Management Deep-Reinforcement-Stock-Trading - A light-weight deep reinforcement learning framework for portfolio management. qtrader - Reinforcement Learning for portfolio management. PGPortfolio - A Deep Reinforcement Learning framework for the financial portfolio management problem. DeepDow - Portfolio optimization with deep learning. ml-quant-trading - PyTorch research stack for mask-aware multi-factor modeling, ML baselines, portfolio optimization, and vectorized backtesting. skfolio - Python library for portfolio optimization built on top of scikit-learn. High Frequency Trading High-Frequency-Trading-Model-with-IB - A high-frequency trading model using Interactive Brokers API with pairs and mean-reversion. 🌟 SGX-Full-OrderBook-Tick-Data-Trading-Strategy - Solutions for high-frequency trading (HFT) strategies using data science approaches (Machine Learning) on Full Orderbook Tick Data. HFT_Bitcoin - Analysis of High Frequency Trading on Bitcoin exchanges. Event Drive 🌟🌟 stockpredictionai - Complete process for predicting stock price movements. 🌟 trump2cash - A stock trading bot powered by Trump tweets. Crypto Currencies Strategies LSTM-Crypto-Price-Prediction - Predicting price trends in crypto markets using an LSTM-RNN for trading. tforce_btc_trader - TensorForce Bitcoin trading bot. Tensorflow-NeuroEvolution-Trading-Bot - A population model that trade cyrpto and breed and mutate iteratively. gekkoga - Genetic algorithm for solving optimization of trading strategies using Gekko. Gekko_ANN_Strategies - ANN trading strategies for the Gekko trading bot. gekko-neuralnet - Neural network strategy for Gekko. bitcoin_prediction - Code for "Bitcoin Prediction" by Siraj Raval on YouTube. DeepAlpha - AI-powered crypto trading bot with 3-model ML ensemble (XGBoost, LightGBM, CatBoost), 12 exchanges via CCXT, walk-forward validated. Technical Analysis QTradeX - A powerful and flexible Python framework for designing, backtesting, optimizing, and deploying algotrading bots quant-trading - Python quantitative trading strategies. Gekko-Bot-Resources - Gekko bot resources. gekko_tools - Gekko strategies, tools etc. gekko RSI_WR - Gekko RSI_WR strategies. gekko HL - Calculate down peak and trade on. EthTradingAlgorithm - Ethereum trading algorithm using Python 3.5 and the library ZipLine. gekko_trading_stuff - Awesome crypto currency trading platform. forex.analytics - Node.js native library performing technical analysis over an OHLC dataset with use of genetic algorithmv. Bitcoin_MACD_Strategy - Bitcoin MACD crossover trading strategy backtest. crypto-signal - Automated crypto trading & technical analysis (TA) bot for Bittrex, Binance, GDAX, and more. Gekko-Strategies - Strategies to Gekko trading bot with backtests results and some useful tools. gekko-gannswing - Gann's Swing trade strategy for Gekko trade bot. Chartscout - Real-time cryptocurrency chart pattern detection with automated alerts using pattern recognition algorithms MarginSafe.ai - AI stock analysis platform specialized in intrinsic value and Wyckoff timing. Wickra - Native library computing 500+ technical-analysis indicators over OHLC data, streaming-first; Rust core with Python, Node.js, WASM and a C ABI (C/C++/C#/Go/Java/R) bindings. PineTS - Open-source Pine Script transpiler and runtime for indicators and strategies in Node.js and browsers, using live or custom market data. Lottery & Gamble LotteryPredict - Use LSTM to predict lottery. Arbitrage ArbitrageBot - Arbitrage bot that currently works on bittrex & poloniex. r2 - Automatic arbitrage trading system powered by Node.js + TypeScript. cryptocurrency-arbitrage - A crypto currency arbitrage opportunity calculator. Over 800 currencies and 50 markets. bitcoin-arbitrage - Bitcoin arbitrage opportunity detector. blackbird - Long / short market-neutral strategy. Data Sources Traditional Markets 🌟 Quandl - Get millions of financial and economic dataset from hundreds of publishers via a single free API. yahoo-finance - Python module to get stock data from Yahoo! Finance. Tushare - TuShare is a utility for crawling historical data of China stocks. Congressional Stock Brain - Free AI-powered tool that scores U.S. STOCK Act congressional trade disclosures by significance. Committee weighting, timing analysis, 537 members tracked. Financial Data - Stock Market and Financial Data API. FinanceKit MCP - MCP server for stock quotes, technical analysis, crypto data, risk metrics, and portfolio analysis. No API keys for core data. Tapetide - Indian market data API and MCP server for NSE/BSE stocks, financials, screeners, and institutional flows. FXMacroData - Macroeconomic and FX data API with central bank announcements, policy rates, inflation, employment, GDP, release calendars, and MCP access for 18 currencies. StockAInsights - Institutional-grade financial statements API with AI extraction from SEC filings — not XBRL. Covers domestic and foreign filers (20-F, 6-K, 40-F), normalized quarterly and annual data. 13F Insight - AI-powered 13F SEC filing tracker. Monitor hedge fund and institutional investor portfolio changes, with smart money move alerts and historical holding comparisons. ValueRay - Technical, quantitative and sentiment data for stocks and ETFs with risk metrics, peer percentiles and market regime signals. Optimized for AI/LLM agents. BenchGecko - AI economy tracking platform. Market cap, funding rounds, AI Bubble Index, company valuations, and compute supply chain data. FilingFirehose - SEC EDGAR JSON API with classified 8-Ks, activist 13D/G tagging, ATM offering detection, and hosted MCP access. SPZCO - Research terminal for U.S. congressional trades, executive disclosures, institutional holdings, and insider filings, with links to source documents. Edgrapi - Metered REST API and hosted MCP service for SEC filings, insider trades, institutional holdings, and company fundamentals. API key required. EarningsCall - API and SDKs for earnings call transcripts, audio, and presentation slides, with speaker identification and Q&A segmentation. The Stall - Pay-per-call API and MCP service aggregating stock, macroeconomic, crypto, and prediction-market data from third-party sources. Crypto Currencies BitBank.nz - AI-powered crypto forecasting and predictions API with machine learning models for 70+ cryptocurrency pairs. CryptoInscriber - A live crypto currency historical trade data blotter. Download live historical trade data from any crypto exchange. CoinPulse - Python SDK for cryptocurrency portfolio tracking with real-time prices, P/L calculations, backtesting, and price alerts. Free tier: 25 req/hr. Gekko-Datasets - Gekko trading bot dataset dumps. Download and use history files in SQLite format. Frostbyte Crypto API - Free real-time cryptocurrency price data API. Supports BTC, ETH, SOL, and 20+ tokens. No signup or API key required for basic endpoints. JSON responses with price, 24h change, market cap, and volume. CoinPaprika API - Cryptocurrency prices, volume, market cap, and historical data via API. Keyless access is available with limits; see plans . DexPaprika API - DEX pool, token, OHLCV, and trade data via API and MCP. Keyless access has rate and usage limits; see plans . Philidor - Institutional-grade DeFi risk scoring for 700+ vaults across 9 protocols and 6 chains. REST API and MCP server (Claude, Cursor, Windsurf). Deterministic 0–10 risk scores, tiers (Prime/Core/Edge), portfolio analysis, oracle monitoring. No API key required. PreReason - Pre-analyzed financial market briefings optimized for AI agent consumption. 17 briefings covering BTC on-chain, macro (Fed balance sheet, M2, Treasury yields), and cross-asset correlations. Returns regime classification, trend signals, and confidence scores in markdown. Satoshi API - Bitcoin fee intelligence API with 108 endpoints for fee estimates, mempool analysis, block data, and mining stats. Self-hostable, Apache 2.0. Sharpe - Agent-ready crypto market intelligence API and MCP server for funding, derivatives, arbitrage, narratives, listings, and news. TBD Predict - Solana-based prediction market for human opinions with an agent CLI and AGENTS.md spec for AI agents to authenticate, list opinion campaigns, and place bets via JSON-friendly commands. 0xArchive - Real-time and historical Hyperliquid and Lighter market data via REST and WebSocket APIs. AgentServices - Crypto market data, on-chain analytics, and FX data via REST and MCP, with free endpoints and metered paid access. News Data WorldMonitor - AI-powered news aggregation, geopolitical monitoring, and infrastructure tracking in a unified situational awareness interface. Alternative Data Adanos Market Sentiment API - Market sentiment API for AI finance agents covering stocks across Reddit, X/Twitter, news, and Polymarket prediction markets with buzz, sentiment, trending, and comparison signals. Pizzint - Pentagon Pizza Index (PizzINT) is a real-time Pentagon pizza tracker that visualizes unusual activity at Pentagon-area pizzerias. It highlights a signal that has historically aligned with late-night, high-tempo operations and breaking news. Prediction Markets Parsec API - Unified prediction market infrastructure for normalized data, execution, and live streams across Polymarket, Kalshi, Opinion, Limitless, and PredictFun. MCP server for AI agent trading. Generous free tier. PolyMind - Real-time Polymarket trading alerts with multi-AI analysis (Groq, Claude, Gemini). Track whale bets, volume spikes, coordinated wallets, and 12 signal types. Free tier available. Live Tennis API - Tennis scores, win probabilities, and historical match results for prediction-market research via REST and WebSocket. History and advanced features require paid plans. Research Tools DDScore - AI-assisted first-pass due diligence for private-company materials, producing a structured 0–100 score and written report across 12 dimensions while checking relevant claims against current public sources. Supports analyst judgement; not investment advice or a replacement for full due diligence. Synthical - AI-powered collaborative environment for Research. 🌟🌟 TensorTrade - Trade efficiently with reinforcement learning. ML-Quant - Quant resources from ArXiv (sanity), SSRN, RePec, Journals, Podcasts, Videos, and Blogs. JAQS - An open source quant strategies research platform. pyfolio - Portfolio and risk analytics in Python. alphalens - Performance analysis of predictive (alpha) stock factors. empyrical - Common financial risk and performance metrics. Used by Zipline and pyfolio. zvt - Zero vector trader. CongressionalStockBrain - AI-powered tool that ingests U.S. STOCK Act congressional trade disclosures and converts them into machine-scored signals for retail investors. WalletLens - Multi-asset portfolio tracker with AI insights, technical analysis, live prices, and local-first data storage. FN2 - AI market analyst for investors: personalized daily briefings, deep stock research, and scheduled agents that watch your watchlist and earnings. Free tier available. WFGY – Open source framework for debugging and stress testing LLM agents and RAG pipelines. Includes a 16 mode failure map and long-horizon stress tests that are useful for financial research agents. ChainPulse - AI-powered Bitcoin network intelligence CLI for natural language queries on mempool, fees, blocks, and mining analysis. CRNG - Contingency RNG, generates random numbers with real market fat tails (K=5-220) and volatility clustering. Matches 86% of real market metrics vs 14% for NumPy. Includes regime detector. Chart Library - Visual chart pattern search engine. Upload a screenshot or type a ticker+date to find the 10 most similar historical chart patterns and see what happened next. 24M+ embeddings, 19K symbols, REST API + MCP server. Coinugget - Real-time RSI signals, price action & volume spikes dashboard for crypto traders. Free, no sign-up required. QuantLink - AI-powered US-equity research terminal with deep-research agents grounded in SEC filings, a fundamental and technical stock screener with backtesting, institutional 13F holder analysis, insider (Form 4) activity, and congressional trade tracking from STOCK Act disclosures. Free tier available. NeuPortal - AI forecasting-accountability lab: every forecast is locked pre-event, Bitcoin-timestamped (OpenTimestamps), and Brier-scored against prediction markets in public. Trading System For Back Test & Live trading Traditional Market System the0 - Self-hosted execution engine for algorithmic trading bots. Supports Python, TypeScript, Rust, C++, C#, Scala, and Haskell. Each bot runs in an isolated container with scheduled or streaming execution. 🌟🌟🌟 OpenBB - AI-powered opensource research and analytics workspace. 🌟🌟 zipline - A python algorithmic trading library. 🌟 TradingView - Get real-time information and market insights. rqalpha - A extendable, replaceable Python algorithmic backtest & trading framework. backtrader - Python backtesting library for trading strategies. kungfu - Kungfu Master trading system. finclaw - AI-native quantitative trading engine with 484 alpha factors, genetic algorithm strategy evolution, walk-forward backtesting and paper trading. Supports A-shares, crypto, and MCP server for AI agent integration. lean - Algorithmic trading engine built for easy strategy research, backtesting and live trading. Combine & Rebuild pylivetrader - Python live trade execution library with zipline interface. CoinMarketCapBacktesting - As backtest frameworks for coin trading strategy. Crypto Currencies zenbot - Command-line crypto currency trading bot using Node.js and MongoDB. bot18 - High-frequency crypto currency trading bot developed by Zenbot. magic8bot - Crypto currency trading bot using Node.js and MongoDB. catalyst - An algorithmic trading library for Crypto-Assets in python. QuantResearchDev - Quant Research dev & Traders open source project. MACD - Zenbot MACD Auto-Trader. abu - A quant trading system base on python. Plugins CoinMarketCapBacktesting - Tests bt and Quantopian Zipline as backtesting frameworks for coin trading strategy. Gekko-BacktestTool - Batch backtest, import and strategy params optimalization for Gekko Trading Bot. TA Lib pandas_talib - A Python Pandas implementation of technical analysis indicators. finta - Common financial technical indicators implemented in Python-Pandas (70+ indicators). tulipnode - Official Node.js wrapper for Tulip Indicators. Provides over 100 technical analysis overlay and indicator functions. techan.js - A visual, technical analysis and charting (Candlestick, OHLC, indicators) library built on D3. Exchange API Do it in real world! Trade It - MCP for trading on common brokerages (Robinhood, ETrade, Schwab, Webull, Public, tastytrade, Coinbase, Kraken so far) IbPy - Python API for the Interactive Brokers on-line trading system. HuobiFeeder - Connect HUOBIPRO exchange, get market/historical data for ABAT trading platform backtest analysis and live trading. ctpwrapper - Shanghai future exchange CTP api. PENDAX - Javascript SDK for Trading/Data API and Websockets for cryptocurrency exchanges like FTX, FTXUS, OKX, Bybit, & More Framework tf-quant-finance - High-performance TensorFlow library for quantitative finance. Visualizing playground - Play with neural networks. netron - Visualizer for deep learning and machine learning models. KLineChart - Highly customizable professional lightweight financial charts GYM Environment 🌟 TradingGym - Trading and Backtesting environment for training reinforcement learning agent. TradzQAI - Trading environment for RL agents, backtesting and training. btgym - Scalable, event-driven, deep-learning-friendly backtesting library. TraderHarness - Contamination-resistant A-share backtesting environment for LLM trading agents, with point-in-time masking, entity/date anonymization, fingerprinted replay, and trajectory (SFT) export. Articles The-Economist - The Economist. nyu-mlif-notes - NYU machine learning in finance notes. Using LSTMs to Turn Feelings Into Trades Others zipline-tensorboard - TensorBoard as a Zipline dashboard. gekko-quasar-ui - An UI port for gekko trading bot using Quasar framework. Floom AI gateway and marketplace for developers, enables streamlined integration and least volatile approach of AI features into products LendTrain - AI-native mortgage refinance plugin for Claude Code with real-time institutional pricing, state-specific closing costs, FHA Streamline/VA IRRRL detection, and regulatory compliance. Uses MCP (Model Context Protocol) to connect LLMs to live mortgage pricing. Registry Broker - Universal AI agent index for discovering trading agents across Virtuals Protocol, NANDA, MCP, and other registries. KeepRule - AI-powered investment discipline tracking platform with curated principles from 26 legendary investors including Buffett, Munger, and Dalio. Helps traders maintain rational decision-making. Philidor - DeFi risk infrastructure for AI agents: MCP server and REST API for vault risk scores, portfolio analysis, and due diligence. No API key. 700+ vaults, 9 protocols, 6 chains. Hindsight - State-of-the-art long-term memory for AI agents by Vectorize. Open source, self-hostable, with integrations for LangChain, CrewAI, MCP, and more. Gives financial trading agents persistent memory across sessions. Other Resource 🌟🌟🌟 Stock-Prediction-Models - Stock-Prediction-Models, Gathers machine learning and deep learning models for Stock forecasting, included trading bots and simulations. 🌟🌟 Financial Machine Learning - A curated list of practical financial machine learning (FinML) tools and applications. This collection is primarily in Python. 🌟 Awesome-Quant-Machine-Learning-Trading - Quant / Algorithm trading resources with an emphasis on Machine Learning. awesome-quant - A curated list of insanely awesome libraries, packages and resources for Quants (Quantitative Finance). FinancePy - A Python Finance Library that focuses on the pricing and risk-management of Financial Derivatives, including fixed-income, equity, FX and credit derivatives. Explore Finance Service Libraries & Projects - Explore a curated list of Fintech popular & new libraries, top authors, trending project kits, discussions, tutorials & learning resources on kandi. AgentMarket - B2A marketplace for AI agents. 189 listings, 28M+ real energy data records, LangChain/MCP integration. MeterCall — One metered API gateway. 21M+ endpoints (payments, SMS, AI, CRMs, gov data). Free tier; pay per call.
2. Related Work, Literature Survey & Algorithmic Foundations
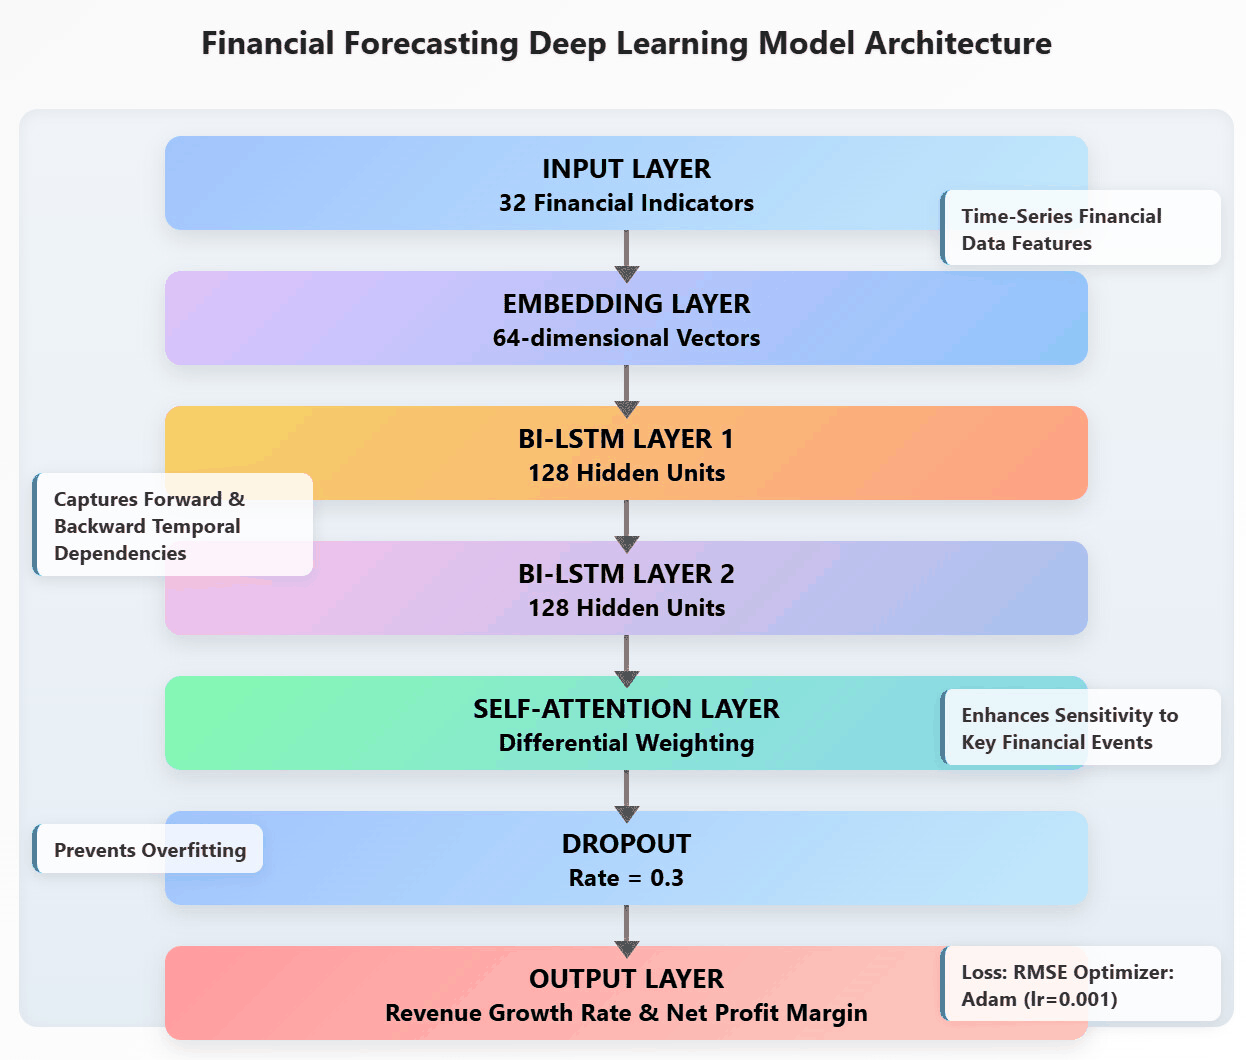
Deep Learning Architectures for Finance Practical deep-learning patterns for financial classification and sequential data, with reproducible synthetic datasets and architecture-oriented examples. Highlights MLP for tabular transaction-risk classification LSTM and GRU for delinquency-index forecasting Scaled dot-product attention from first principles Compact Transformer-style classifier for transaction sequences Baseline-first evaluation and architecture selection by data structure Tech stack Python · NumPy · pandas · scikit-learn · TensorFlow/Keras Repository structure src/tabular_mlp.py — tabular financial classification src/sequence_models.py — LSTM/GRU forecasting workflow src/attention_transformer.py — attention mechanics and sequence classification requirements.txt Run python -m venv .venv # Windows: .venv\Scripts\activate # Linux/macOS: source .venv/bin/activate pip install -r requirements.txt python src/tabular_mlp.py python src/sequence_models.py python src/attention_transformer.py All examples use synthetic data. The objective is to demonstrate architecture choice, evaluation discipline and reproducible implementation rather than depend on proprietary financial datasets.
3. Dataset Ingestion, Preprocessing & Stochastic Augmentations
Machine Learning for Finance A CQF elective with Dr. Yves J. Hilpisch, The Python Quants GmbH General resources: http://tpq.io http://hilpisch.com Wifi You can use the following wifi in this venue: SSID Fitch Guest PW Ft1ch#2016#! Abstract This CQF elective is about machine learning and deep learning with Python applied to finance. It starts with techniques to retrieve financial data from open data sources and covers Python packages like NumPy, pandas, scikit-learn and TensorFlow. It provides the basis to further explore these recent developments in data science to improve traditional financial tasks such as the pricing of American options or the prediction of future stock market movements. Among other, the elective covers: Getting and working with financial time series data in Python Using linear OLS regression to predict financial prices & returns Using scikit-learn for machine learning with Python Application to the pricing of American options by Monte Carlo simulation Applying logistic regression to classification problems Predicting stock market returns as a classification problem Using TensorFlow for deep learning with Python Using deep learning for predicting stock market returns Overview slides under http://hilpisch.com/cqf_ml_elective.pdf Python Download and install Miniconda 3.6 from https://conda.io/miniconda.html If you have either Miniconda or Anaconda installed there is not need to install anything new. conda create -n elective python=3.6 (source) activate elective conda install numpy pandas=0.19 scikit-learn matplotlib conda install pandas-datareader pytables conda install ipython jupyter jupyter notebook Installing TensorFlow : https://www.tensorflow.org/install/ Finance Download the paper by Longstaff and Schwartz (2001) about the Least-Squares Monte Carlo algorithm to price American options from Paper about LSM algorithm Basic Definitions "You can think of deep learning, machine learning and artificial intelligence [AI] as a set of Russian dolls nested within each other, beginning with the smallest and working out. Deep learning is a subset of machine learning, which is a subset of AI. ... That is, all machine learning counts as AI, but not all AI counts as machine learning. For example, symbolic logic (rules engines, expert systems and knowledge graphs) as well as evolutionary algorithms and Baysian statistics could all be described as AI, and none of them are machine learning." " Neural networks are a set of algorithms, modeled loosely after the human brain, that are designed to recognize patterns. They interpret sensory data through a kind of machine perception, labeling or clustering raw input. The patterns they recognize are numerical, contained in vectors, into which all real-world data, be it images, sound, text or time series, must be translated." " Deep learning maps inputs to outputs. It finds correlations. It is known as a 'universal approximator', because it can learn to approximate the function f(x) = y between any input x and any output y, assuming they are related through correlation or causation at all. In the process of learning, a neural network finds the right f, or the correct manner of transforming x into y, whether that be f(x) = 3x + 12 or f(x) = 9x - 0.1." "All classification tasks depend upon labeled datasets; that is, humans must transfer their knowledge to the dataset in order for a neural to learn the correlation between labels and data. This is known as supervised learning. ... Any labels that humans can generate, any outcomes you care about and which correlate to data, can be used to train a neural network." Source: https://deeplearning4j.org Machine Learning Here some resources to get a first overview of basic machine learning concepts and logistic regression for classification: Visual Guide to Basics of Neural Networks Logistic Regression Basics & Algorithm Generalized Linear Models in scikit-learn Neural Networks Here some resources to get a first overview of neural networks : A Neural Network in 11 Lines of Python Introduction to Deep Neural Networks A Guide to Deep Learning Neural Networks and Deep Learning (free e-book) TensorFlow Some resources to get started with Google's TensorFlow package for deep learning: Hello, TensorFlow! TensorFlow Tutorials Data Download a HDF5 database file, containing a single pandas DataFrame object with hitorical equites data, from http://hilpisch.com/equities.h5
4. Neural Network Backbone, Layer Specifications & Loss Formulations
📈 AI in Quantitative Finance — Deep Learning for Portfolio Management This project implements the end-to-end pipeline described in "Artificial Intelligence in Quantitative Finance: Leveraging Deep Learning for Smarter Portfolio Management and Asset Allocation" . We combine LSTM and Transformer models for financial return forecasting , integrate the predictions into a dynamic portfolio allocation strategy , and evaluate using comprehensive backtesting and statistical testing . 📂 Project Structure project-root/ │ ├── data/ │ ├── raw/ # Raw downloaded price data │ ├── processed/ # Preprocessed features & targets │ │ ├── features_scaled.csv │ │ ├── targets.csv │ │ ├── scaler_features.pkl │ │ └── index_splits.json │ ├── notebooks/ │ ├── 01_data_exploration.ipynb │ ├── 02_model_training.ipynb │ ├── 03_backtest_and_eval.ipynb │ ├── results/ │ ├── checkpoints/ # Saved LSTM & Transformer models by timestamp │ │ ├── lstm/ │ │ └── transformer/ │ ├── figures/ # Plots & visualizations │ ├── metrics_lstm.csv │ ├── metrics_transformer.csv │ ├── predictions_lstm.csv │ └── predictions_transformer.csv │ ├── src/ │ ├── data_fetch.py # Step 1: Download financial data │ ├── preprocessing.py # Step 2: Build features, scale, save datasets │ ├── train.py # Step 3: Train LSTM or Transformer models │ ├── predict.py # Step 5: Generate rolling forecasts │ ├── optimizer.py # Portfolio optimization logic │ ├── backtest.py # Step 5: Backtesting engine │ ├── metrics.py # Step 6: Performance metrics & statistical tests │ ├── evaluate_and_plot.py # Step 6: Run evaluation, save metrics & plots │ └── datasets.py # SequenceDataset loader │ └── environment.yml # Conda environment with dependencies\ ⚙️ Pipeline Overview The workflow follows six main steps : Step 1 — Data Collection Script: src/data_fetch.py Fetches historical financial price data from the internet (e.g., Yahoo Finance). Saves raw prices to data/raw/ . Run: python src/data_fetch.py --start 2010-01-01 --end 2023-12-31 Step 2 — Data Preprocessing Script: src/preprocessing.py Builds predictive features (technical indicators, returns, rolling stats). Scales features (StandardScaler) using train split only. Saves: features_scaled.csv , targets.csv , scaler_features.pkl , index_splits.json Run: python src/preprocessing.py --data data/processed/prices_usd.csv Step 3 — Model Training Script: src/train.py Defines LSTM and Transformer architectures. Saves checkpoints to results/checkpoints/<model>/<timestamp>/epoch_<n>.pth Run: # LSTM python src/train.py --model lstm --epochs 50 # Transformer python src/train.py --model transformer --epochs 50 Step 4 — Forecast Generation Script: src/predict.py Loads latest checkpoint for the chosen model. Generates rolling walk-forward predictions for the test set. Saves to results/predictions_<model>.csv Run: python src/predict.py --model-type lstm python src/predict.py --model-type transformer Step 5 — Portfolio Optimization & Backtest Script: src/optimizer.py → Mean-Variance Optimizer. src/backtest.py → Computes portfolio returns from weights & realized returns. Step 6 — Evaluation & Plots Script: src/evaluate_and_plot.py Loads predictions & realized returns. Computes: Annualized return, volatility, Sharpe ratio, Sortino ratio, Calmar ratio. RMSE & directional accuracy for forecasts. Statistical tests: Paired t-test, Jobson-Korkie-Memmel. Saves: Metrics CSV → results/metrics_<model>.csv Plots → results/figures/ Run: python src/evaluate_and_plot.py --model-type lstm python src/evaluate_and_plot.py --model-type transformer 📊 Outcomes LSTM & Transformer deep learning models for return forecasting. Fully automated data-to-decisions pipeline: Data fetching → Feature engineering → Model training → Prediction → Portfolio construction → Evaluation. Dynamic portfolio allocation using forecasts. Comprehensive evaluation with statistical significance testing. Visual outputs for cumulative returns, rolling Sharpe ratio, and portfolio weights. 🚀 What This Project Achieves Demonstrates state-of-the-art AI techniques (LSTM, Transformer) in finance. Provides a research-ready backtesting framework . Bridges ML predictions with portfolio management. Produces replicable & extensible results for further experimentation. 💻 Environment Setup conda env create -f environment.yml conda activate project 🏁 Quickstart # 1. Fetch data python src/data_fetch.py --start 2010-01-01 --end 2023-12-31 # 2. Preprocess python src/preprocessing.py # 3. Train model python src/train.py --model lstm --epochs 50 # 4. Predict python src/predict.py --model-type lstm # 5. Evaluate python src/evaluate_and_plot.py --model-type lstm
5. Training Protocol, Convergence Behavior & Experimental Evaluation
A Survey of Financial AI: Architectures, Advances and Open Challenges Resources: Paper , Slides , Cite This repository is a curated collection of high-quality papers presented at top Computer Science (CS) conferences related to Artificial Intelligence (AI) applications in finance. The aim is to offer a comprehensive review of these papers, summarize key findings, and analyze their contributions to the field. This list extends an earlier collection: Awesome-LLM-Agents . Price Prediction Formulation For Price Prediction tasks, the objectives are forecasting of continuous data, for (1) stock price, (2) earning, or (3) volatility. Models to learn feature representations commonly include some combinations of: (1) attention-based models (2) spatial-temporal models (3) graph models Auto-regressive self-supervised learning is commonly seen in pre-training the financial data representation, whereas supervised finetuning (SFT) is used in post-training for the prediction downstream task. Papers MDGNN: Multi-Relational Dynamic Graph Neural Network for Comprehensive and Dynamic Stock Investment Prediction, AAAI'24 ( Paper ) MASTER: Market-Guided Stock Transformer for Stock Price Forecasting, AAAI'24 ( Paper , Code ) DoubleAdapt: A Meta-learning Approach to Incremental Learning for Stock Trend Forecasting, KDD'23 ( Paper ) Double-Path Adaptive-correlation Spatial-Temporal Inverted Transformer for Stock Time Series Forecasting, KDD'25 ( Paper ) Stock Movement Prediction Based on Bi-typed Hybrid-relational Market Knowledge Graph via Dual Attention Networks, TKDE'23 ( Paper ) GARCH-Informed Neural Networks for Volatility Prediction in Financial Markets, ArXiv'24 ( Paper ) DiffSTOCK: Probabilistic relational Stock Market Predictions using Diffusion Models, ICASSP'24 ( Paper ) From News to Forecast: Iterative Event Reasoning in LLM-Based Time Series Forecasting, NeurIPS'24 ( Paper ) Trend/Movement Classification Formulation Trend/Movement Classification is commonly binary classification task that predicts the market movement (up or down) on a future date. Basic building blocks (i.e. models) for feature representation and downstream task are similar to that in Price Prediction. Papers Multi-relational Graph Diffusion Neural Network with Parallel Retention for Stock Trends Classification, ICASSP'24 ( Paper ) Saliency-Aware Interpolative Augmentation for Multimodal Financial Prediction, COLING'24 ( Paper ) ECHO-GL: Earnings Calls-Driven Heterogeneous Graph Learning for Stock Movement Prediction, AAAI'24 ( Paper ) Trade When Opportunity Comes: Price Movement Forecasting via Locality-Aware Attention and Iterative Refnement Labeling, IJCAI'24 ( Paper ) MANA-Net: Mitigating Aggregated Sentiment Homogenization with News Weighting for Enhanced Market Prediction, CIKM'24 ( Paper ) Learning to Generate Explainable Stock Predictions using Self-Reflective Large Language Models, WWW'24 ( Paper ) Ranking-based Stock Selection Formulation Ranking-based Stock Selection is modelled as a ranking task that outputs the rank of a pool of stocks based on some values such as predicted earnings or risk adjusted earnings. Basic building blocks (i.e. models) for feature representation and downstream task are similar to that in Price Prediction and Trend Classification. Papers CI-STHPAN: Pre-trained Attention Network for Stock Selection with Channel-Independent Spatio-Temporal Hypergraph, AAAI'24 ( Paper ) Automatic De-Biased Temporal-Relational Modeling for Stock Investment Recommendation, IJCAI'24 ( Paper ) RSAP-DFM: Regime-Shifting Adaptive Posterior Dynamic Factor Model for Stock Returns Prediction, IJCAI'24 ( Paper ) Relational Temporal Graph Convolutional Networks for Ranking-Based Stock Prediction, ICDE'23 ( Paper ) Portfolio Optimization Formulation For portfolio optimization, the objectives are variants of asset allocation, i.e., optimizing the portfolio weights. The decision making processes are commonly modelled as Markov Decision Process (MDP), Partially Observed MDP (POMDP), Hierachical MDP (HMDP) and Hidden Markov Model (HMM). In terms of ML models, Reinforcement Learning is a norm. Papers Developing A Multi-Agent and Self-Adaptive Framework with Deep Reinforcement Learning for Dynamic Portfolio Risk Management, AAMAS'24 ( Paper ) Trend-Heuristic Reinforcement Learning Framework for News-Oriented Stock Portfolio Management, ICASSP'24 ( Paper ) Reinforcement Learning with Maskable Stock Representation for Portfolio Management in Customizable Stock Pools, WWW'24 ( paper ) FreQuant: A Reinforcement-Learning based Adaptive Portfolio Optimization with Multi-frequency Decomposition, KDD'24 ( paper ) Risk-Managed Sparse Index Tracking Via Market Graph Clustering, ICASSP'24 ( Paper ) Mitigating Extremal Risks: A Network-Based Portfolio Strategy, ArXiv'24 ( Paper ) Improving Portfolio Optimization Results with Bandit Networks, ArXiv'24 ( paper ) Quantitative Trading Formulation For Quantitative Trading, the objectives are trading actions (long/short/hold)and its attributes (amount, price, etc.). The decision making models are similar to that in Portfolio Optimization. Papers Optimizing Trading Strategies in Quantitative Markets using Multi-Agent Reinforcement Learning, ICASSP'24 ( Paper ) EarnHFT: Efficient Hierarchical Reinforcement Learning for High Frequency Trading, AAAI'24 ( Paper ) MacMic: Executing Iceberg Orders via Hierarchical Reinforcement Learning, IJCAI'24 ( Paper ) IMM: An Imitative Reinforcement Learning Approach with Predictive Representation Learning for Automatic Market Making, IJCAI'24 ( Paper ) Hierarchical Reinforced Trader(HRT): A Bi-Level Approach for Optimizing Stock Selection and Execution, ArXiv'24 ( Paper ) MacroHFT: Memory Augmented Context-aware Reinforcement Learning On High Frequency Trading, KDD'24 ( Paper ) Efficient Continuous Space Policy Optimization for High-frequency Trading, KDD'23 ( Paper ) StockFormer: Learning Hybrid Trading Machines with Predictive Coding, IJCAI'23 ( Paper ) A Multimodal Foundation Agent for Financial Trading: Tool-Augmented, Diversified, and Generalist, KDD'24 ( Paper ) Automate Strategy Finding with LLM in Quant investment, ArXiv'24 ( Paper ) Knowledge Retrieval and Augmentation This is a loosely categorised task that involved a combination of (1) Information Retrieval (2) Data Augmentation (3) Data Labelling (4) Prompt Engineering (5) Simulation (6) Others Calling this "Knowledge Retrieval and Augmentation" should cover most of the primary objectives of the papers. Retrieval and Augmentation Extracting Financial Events from Raw Texts via Matrix Chunking, COLING'24 ( Paper ) Large Language Models as Financial Data Annotators: A Study on Effectiveness and Efficiency, COLING'24 ( Paper ) FinReport: Explainable Stock Earnings Forecasting via News Factor Analyzing Model, WWW'24 ( Paper ) Prompt Engineering Prompting for Numerical Sequences: A Case Study on Market Comment Generation, COLING'24 ( Paper ) Temporal Relational Reasoning of Large Language Models for Detecting Stock Portfolio Crashes, ArXiv'24 ( Paper ) Agentic Simulations EconAgent: Large Language Model-Empowered Agents for Simulating Macroeconomic Activities, ACL'24 ( Paper , Code ) When AI Meets Finance (StockAgent): Large Language Model-based Stock Trading in Simulated Real-world Environments, ArXiv'24 ( Paper , Code ) Datasets Though the papers primarily propose some datasets, they also contribute to a variety of the abovementioned tasks. Papers AlphaFin: Benchmarking Financial Analysis with RetrievalAugmented Stock-Chain Framework, COLING'24 ( Paper , Code ) Market-GAN: Adding Control to Financial Market Data Generation with Semantic Context, AAAI'24 ( Paper , Code ) FNSPID: A Comprehensive Financial News Dataset in Time Series, KDD'24 ( Paper , Dataset , Code ) StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series, AAAI'23 ( Paper , Code ) Time Series Models This section includes some general time-series models that were recently proposed. One may get inspirations in model designs, or directly apply them on financial time-series data. Papers TimeMixer: Decomposable Multiscale Mixing for Time Series Forecasting, ICLR'24 ( Paper , Code ) MOMENT: A Family of Open Time-series Foundation Models, ICML'24 ( Paper , Code ) Timer: Generative Pre-trained Transformers Are Large Time Series Models, ICML'24 ( Paper , Code ) TimesNet: Temporal 2d-variation modeling for general time series analysis, ICLR’23 ( Paper , Code ) A Time Series is Worth 64 Words: Long-term Forecasting with Transformers, ICLR'23 ( Paper , Code ) Survey This section includes some other survey papers on LLM for Finance Papers A Survey of Large Language Models in Finance (FinLLMs), ArXiv'24 ( Paper ) A Survey of Large Language Models for Financial Applications: Progress, Prospects and Challenges, ArXiv'24 ( Paper ) Large Language Model Agent in Financial Trading: A Survey, ArXiv'24 ( Paper ) Revolutionizing Finance with LLMs: An Overview of Applications and Insights, ArXiv'24 ( Paper ) Citation Please cite the repo if the content assists your work. @article{liu2024survey, title={A Survey of Financial AI: Architectures, Advances and Open Challenges}, author={Liu, Junhua}, journal={arXiv:2411.12747}, url={https://github.com/junhua/awesome-finance-ai-papers/}, year={2024}, publisher={arXiv} }
Model Figures & Evaluation Curves (4 Images)
Deep Learning Execution Pipeline
(Preprocessing)
(Feature Extraction)
(Self-Attention)
(Loss Optimization)